Personal Finance Tips for 2026: 12 Habits That Build Real Wealth
The most valuable personal finance tips for 2026 have almost nothing to do with picking the perfect stock. They are about habits: the small, repeatable decisions that compound quietly in the background. If you fix your systems, the numbers tend to look after themselves. This guide focuses on behaviour you can start today, whatever your income.
Inflation, rising rents, and unpredictable side incomes make steady routines more important than ever. Below are the habits that consistently separate people who feel in control of their money from those who feel chased by it.
Start With Your Money Mindset
Before spreadsheets, fix the story you tell yourself about money. People who believe they are “bad with money” rarely open their banking app, and avoidance is where most financial problems hide and grow.
Reframe money as a tool, not a test of character. One missed budget does not make you a failure; it is simply data for next month. This single shift makes every other habit easier to keep.
Personal Finance Tips for Everyday Spending
Day-to-day spending is where fortunes leak. The fix is not deprivation; it is friction. Make good choices easy and impulse choices slightly harder.
- Use a 24-hour rule for any non-essential purchase over a set amount.
- Unsubscribe from retailer emails that manufacture fake urgency.
- Cook one extra meal each week to cut delivery spending.
- Review subscriptions every quarter and cancel what you forgot you had.
These everyday personal finance tips work because they target repeated behaviour, not one-off events. Small, frequent savings beat a single dramatic cutback that never lasts.
Automate Saving Before You See the Money
The oldest rule in personal finance still wins: pay yourself first. If savings leave your account the day your salary arrives, you never build a lifestyle around money you were meant to keep.
- Set an automatic transfer for payday itself, not month-end.
- Start with a figure you will not notice, then raise it each quarter.
- Keep your emergency fund in a separate, slightly inconvenient account.
- Route any raise or bonus straight to savings before lifestyle creep catches it.
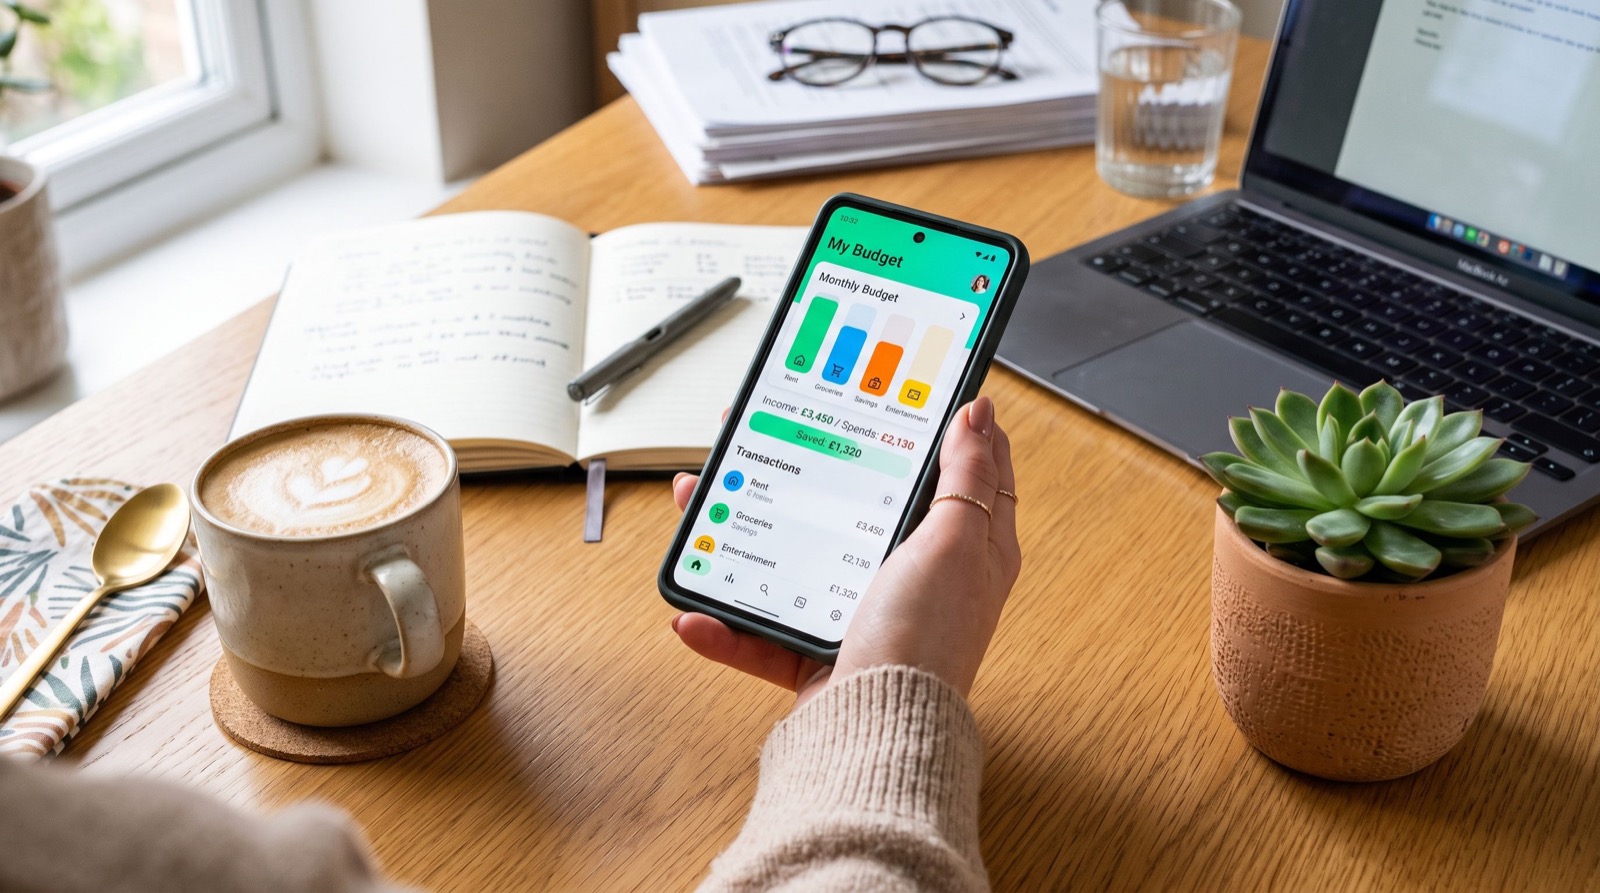
Automation is easiest when you pair it with the best money apps, which can round up purchases and sweep spare change into savings without you lifting a finger.
Build an Emergency Fund and Kill Bad Debt
An emergency fund is the shock absorber that keeps one bad month from becoming one bad year. Most experts suggest three to six months of essential expenses held in cash you can reach quickly.
High-interest debt works against you faster than almost any investment works for you. The Federal Reserve tracks consumer credit trends showing that revolving balances remain a major drag on household budgets, so clearing them is often the highest-return move available.
Snowball vs Avalanche
Two proven methods tackle debt. Choose the one you will actually stick to.
| Method | How It Works | Best For |
|---|---|---|
| Snowball | Pay smallest balance first | People who need quick wins |
| Avalanche | Pay highest interest first | People who want to save the most |
| Hybrid | One quick win, then avalanche | Most households |
Grow Wealth Through Boring, Consistent Investing
Once your emergency fund is solid and bad debt is gone, investing becomes the engine of long-term wealth. The winning strategy is dull on purpose: invest a fixed amount every month into low-cost, diversified funds and leave it alone.
Time in the market beats timing the market. A modest sum invested consistently for twenty years usually outperforms a larger sum invested in bursts of excitement and panic. Set it, automate it, and resist the urge to tinker.
An Original Tip: The 1% Upgrade
Here is a practical trick most lists skip. Instead of overhauling everything at once, upgrade one number by one percent each quarter. Increase your savings rate by 1%, negotiate a 1% lower insurance premium, or shift 1% more toward investments. The changes are painless in isolation, yet after two years they stack into a transformed financial picture.
If you run a growing business and want these same principles applied to your company’s cash flow, working with reputable service experts helps you separate personal and business finances before they tangle.
Track Your Net Worth, Not Just Your Budget
Budgets tell you about this month; net worth tells you about your life. Your net worth is simply everything you own minus everything you owe, and tracking it quarterly is the single clearest measure of whether your habits are working.
The number will dip and climb, and that is fine. What matters is the trend line over years, not the noise over weeks. Watching net worth also keeps you motivated during long debt payoffs, because progress becomes visible even when your checking balance looks flat.
- Assets: cash, savings, investments, retirement accounts, property.
- Liabilities: credit cards, student loans, car finance, mortgage.
- Net worth: assets minus liabilities, reviewed every three months.
Plan for Taxes and Big Goals
Smart savers think a year ahead. Set money aside for predictable costs such as taxes, insurance renewals, and annual subscriptions so they never ambush your budget. A dedicated “sinking fund” for each large expense turns a painful one-off hit into a series of painless monthly deposits.
Name your goals too. A savings account labelled “house deposit 2028” is far more motivating than a vague balance, and research on behaviour consistently shows that concrete, named goals get funded more reliably than abstract ones.
Frequently Asked Questions
What are the most important personal finance tips for beginners?
Start by tracking every expense for one month, build a small emergency fund, and automate a fixed saving transfer on payday. These three habits create a stable base before you worry about investing or optimising returns.
How much of my income should I save in 2026?
A common target is 20% of take-home pay, split between emergency savings and long-term investing. If that feels impossible, start at 5% and raise it by one percent each quarter until you reach a comfortable rate.
Should I pay off debt or invest first?
Clear high-interest debt before investing, because its guaranteed cost usually exceeds likely investment returns. Keep a small emergency fund alongside your debt payoff so a surprise expense does not push you back onto the credit card.
Do budgeting apps really help?
Yes, when used consistently. Apps remove the friction of manual tracking and send reminders that keep habits alive. The tool matters less than whether you open it each week and act on what it shows.
Final Word
The best personal finance tips for 2026 are quiet, repeatable, and almost boring, and that is exactly why they work. Fix your mindset, automate your saving, crush bad debt, and let consistent investing compound. Master the systems and wealth stops being a mystery and becomes a habit you simply maintain.